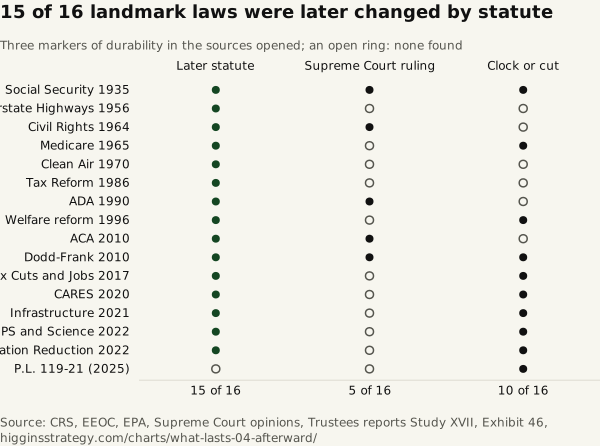
15 of 16 landmark laws were later changed by statute
Source. CRS, EEOC, EPA, Supreme Court opinions, Trustees reports
Method and data
Method. Three markers of durability. Changed = a later public law amended, extended or partly repealed the law, documented in a source opened (for the 1956 highway act, nine successor authorization acts). Ruled on = a Supreme Court decision addressing the law, found in a source opened; in the sources opened, five laws have one. Clock = a documented date, past or future, on which provisions of the law or a program it created expire, are depleted or need extension, or a documented cut to its funding; each dot is one distinct item, so the 1956 highway act and the ACA are hollow because their successor items are counted under the infrastructure law and the Inflation Reduction Act. Ten laws have a clock: five with dates ahead on October 18, 2026, four with dates passed or resolved, one cut. A hollow dot means none was found in the sources opened, not that none exists.
| Law | Changed by a later statute | Later statute | Supreme Court ruling | Ruling | Clock or cut | Clock status | Clock or cut detail |
|---|---|---|---|---|---|---|---|
| Social Security 1935 | Y | Social Security Amendments of 1956 (P.L. 84-880) added disability insurance; Social Security Amendments of 1983 (P.L. 98-21) raised the full retirement age from 65 to 67 and made up to 50% of benefits taxable | Y | Supreme Court, 301 U.S. 619 (1937-05-24): upheld Title II old-age benefits | Y | ahead | 2026 Trustees: OASI reserves depleted in Q4 2032 with 78% of scheduled benefits payable; combined OASDI Q3 2034, 83% |
| Interstate Highways 1956 | Y | Nine multiyear surface transportation acts enacted 1978-2021 succeeded it; IIJA is the latest (successor acts, not amendments to the 1956 text) | N | none found in sources opened | N | not counted here: the successor clocks are counted under Infrastructure 2021 (IIJA authorizations extended through 2026-12-11 by H.R. 6500, P.L. 119-103); earlier acts needed 1 to 12 short-term extensions each (1991-2015 acts) | |
| Civil Rights 1964 | Y | Civil Rights Act of 1991 added compensatory and punitive damages for intentional employment discrimination | Y | Heart of Atlanta Motel v. United States, 379 U.S. 241 (1964-12-14): Title II valid under the Commerce Clause | N | no dated clock or cut found in sources opened | |
| Medicare 1965 | Y | 1972 expansion to the disabled and people with end-stage renal disease; Medicare Modernization Act of 2003 (P.L. 108-173) created Part D | N | none found in sources opened | Y | ahead | 2026 Trustees: HI reserves depleted in Q2 2033 with 89% of scheduled benefits payable |
| Clean Air 1970 | Y | Clean Air Act Amendments of 1977 and 1990 | N | none found in sources opened | N | no dated clock or cut found in sources opened | |
| Tax Reform 1986 | Y | Omnibus Budget Reconciliation Acts of 1990 and 1993, the 2001 and 2003 tax acts and the Working Families Tax Relief Act of 2004 each changed the individual rate structure | N | none found in sources opened | N | no dated clock or cut found in sources opened | |
| ADA 1990 | Y | ADA Amendments Act of 2008 (P.L. 110-325, approved 2008-09-25; House passed H.R. 3195 402–17 on 2008-06-25) restored its intended scope | Y | Two decisions, in 1999 and 2002, narrowed it, per Congress's findings in the 2008 Act (EEOC page) | N | no dated clock or cut found in sources opened | |
| Welfare reform 1996 | Y | Deficit Reduction Act of 2005 (P.L. 109-171) reauthorized TANF through FY2010; Fiscal Responsibility Act of 2023 (P.L. 118-5) changed work standards | N | none found in sources opened | Y | ahead | TANF authorization expired 2002-09-30; 13 temporary extensions 2002-2006; short-term extensions since FY2010; latest (P.L. 119-75) runs through 2026-12-31 |
| ACA 2010 | Y | P.L. 115-97 effectively eliminated the individual mandate penalty from tax year 2019; repeal bill H.R. 3762 passed both chambers and was vetoed 2016-01-08; House passed H.R. 1628 217–213 (2017-05-04), Senate last vote 49–51 (2017-07-28) | Y | Supreme Court, 567 U.S. 519 (2012-06-28), brought by the National Federation of Independent Business: mandate upheld under the taxing power, Medicaid expansion limited as written; California v. Texas (2021-06-17): plaintiffs lacked standing | N | not counted here: the enhanced premium tax credits (extended through 2025 by P.L. 117-169) expired and are counted under Inflation Reduction 2022; marketplace enrollment then fell 13%, from 22.1 million (2025) to 19.2 million (Feb. 2026) | |
| Dodd-Frank 2010 | Y | P.L. 115-174 (signed 2018-05-24; Senate 67–31, House 258–159) eased provisions; P.L. 119-21 cut the CFPB funding cap 46% in FY2025 ($823 million to $446 million) | Y | Seila Law v. CFPB (2020-06-29): CFPB director removal protection unconstitutional, severable from the rest of the Act | Y | cut | CFPB funding cap cut 46% in FY2025 by P.L. 119-21 ($823 million to $446 million) |
| Tax Cuts and Jobs 2017 | Y | P.L. 119-21 made the individual income tax rates permanent | N | none found in sources opened | Y | passed or resolved | Individual rate reductions were made temporary (through 2025) to avoid violating the Byrd rule; P.L. 119-21 made them permanent |
| CARES 2020 | Y | P.L. 116-260 extended some bank and credit union provisions | N | none found in sources opened | Y | passed or resolved | Provisions were set to expire by the end of 2020 or the end of the national emergency; many remained in effect, some expired, and P.L. 116-260 extended some |
| Infrastructure 2021 | Y | H.R. 6500 (P.L. 119-103) extended the surface transportation authorizations through 2026-12-11 | N | none found in sources opened | Y | ahead | Authorizations cover FY2022-FY2026 and were extended three months, through 2026-12-11 (H.R. 6500, P.L. 119-103); this item also covers the 1956 highway act's successor acts |
| CHIPS and Science 2022 | Y | P.L. 119-21 raised the semiconductor investment tax credit from 25% to 35% | N | none found in sources opened | Y | ahead | FY2026 (ended 2026-09-30) is the final year of Commerce incentives funding; the 35% credit applies only to projects that begin construction before 2026-12-31 |
| Inflation Reduction 2022 | Y | P.L. 119-21 repealed three electric vehicle tax credits and changed clean electricity and manufacturing credits | N | none found in sources opened | Y | passed or resolved | The enhanced premium tax credit extension it enacted (tax years 2023-2025) expired; this item also covers the ACA's premium credits |
| P.L. 119-21 (2025) | N | no amending law found in sources opened | N | none found in sources opened | Y | passed or resolved | Section 71113, a one-year ban on federal Medicaid payments to certain providers, was set to expire 2026-07-03; what followed the date was not found |